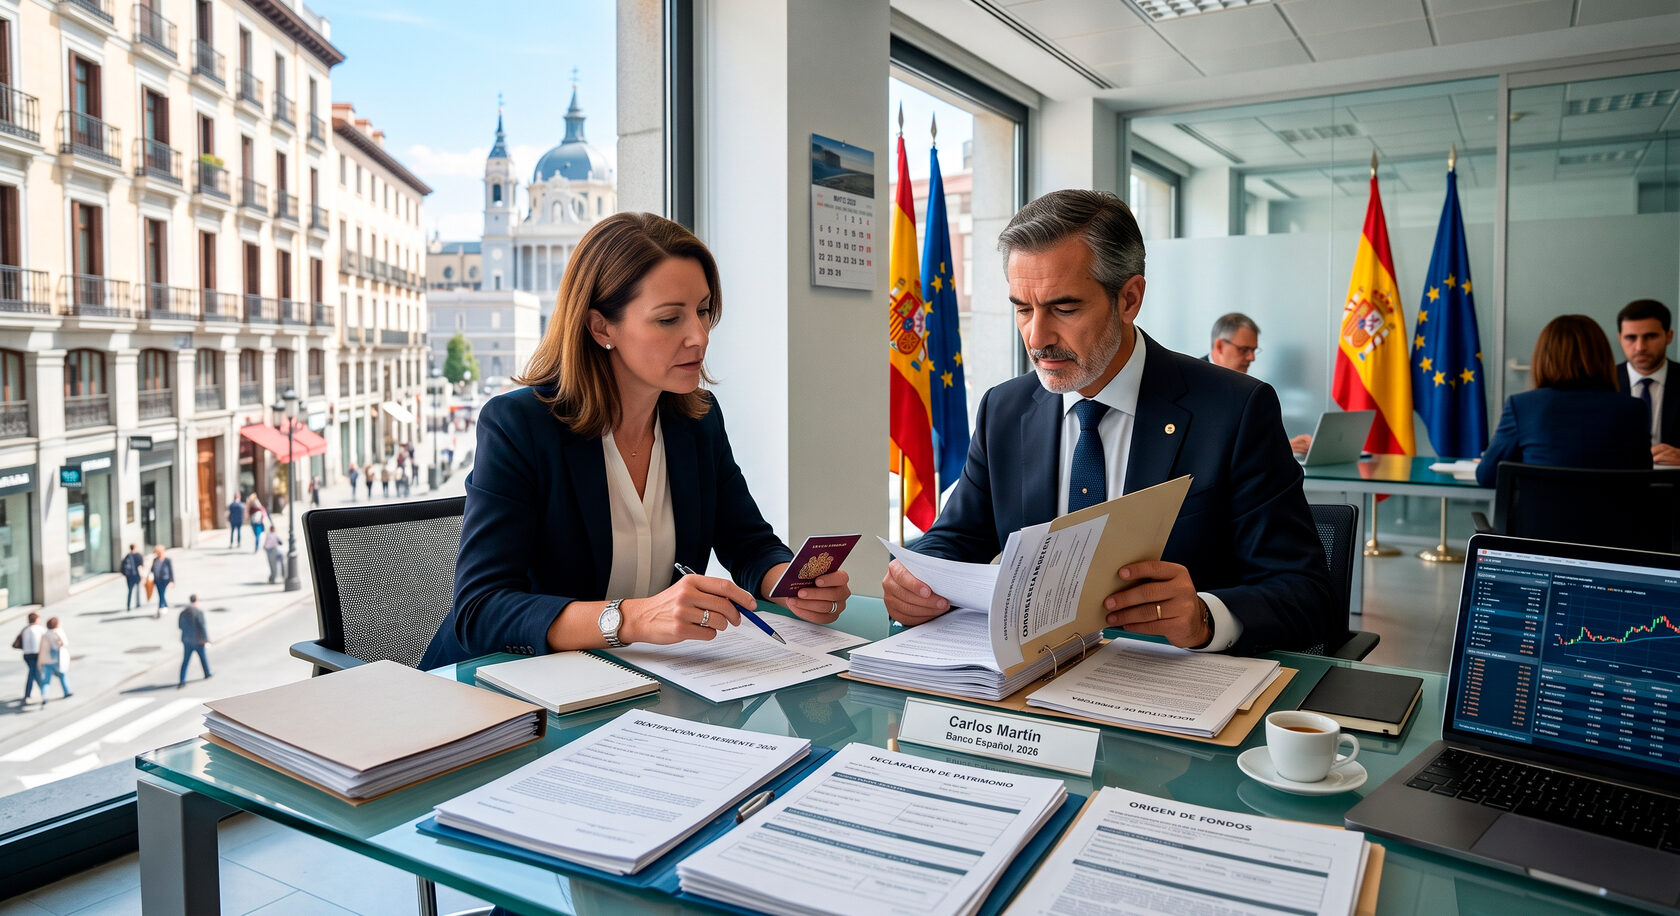
The procedure for integrating foreign capital into the financial system of the European Union has undergone radical transformations. Opening a bank account in Spain for non-residents 2026 represents a highly complex, multi-level process requiring flawless legal and financial preparation. The era of formal, superficial checks has permanently concluded. The modern banking sector operates under a strict presumption of capital guilt. Every client must prove the absolute legality of every single cent. This article serves as an exhaustive analytical protocol. It was developed by practicing real estate and investment experts at Angel Property. This guide ensures successful navigation of banking controls when preparing to acquire assets within the Kingdom of Spain.
Financial institutions in Spain operate under severe pressure from European directives and national regulators. Any transaction involving the transfer of funds from outside the European Economic Area (EEA) is automatically flagged by algorithms as high-risk. This reality demands that the applicant provide a highly structured, logically consistent, and fully documented dossier. A single error in forming the document package leads to immediate service denial. Poor translation quality or a gap in the chronological origin of funds yields the same result. Consequently, the applicant faces inclusion in interbank stop-lists and the potential freezing of assets.
Successful opening a bank account in Spain for non-residents 2026 relies entirely on understanding the internal logic of financial monitoring departments. The bank does not evaluate the client based on their overall wealth or social status. Instead, the bank strictly assesses the potential legal and reputational risks that this specific client might introduce to the institution. Therefore, the primary objective of the applicant is to systematically minimize these risks through absolute, undeniable transparency.
Financial institutions in Spain operate under severe pressure from European directives and national regulators. Any transaction involving the transfer of funds from outside the European Economic Area (EEA) is automatically flagged by algorithms as high-risk. This reality demands that the applicant provide a highly structured, logically consistent, and fully documented dossier. A single error in forming the document package leads to immediate service denial. Poor translation quality or a gap in the chronological origin of funds yields the same result. Consequently, the applicant faces inclusion in interbank stop-lists and the potential freezing of assets.
Successful opening a bank account in Spain for non-residents 2026 relies entirely on understanding the internal logic of financial monitoring departments. The bank does not evaluate the client based on their overall wealth or social status. Instead, the bank strictly assesses the potential legal and reputational risks that this specific client might introduce to the institution. Therefore, the primary objective of the applicant is to systematically minimize these risks through absolute, undeniable transparency.
Why Spanish banks became "difficult" in 2026
In 2026, the complexity of banking procedures is driven by the implementation of the EU's Sixth Anti-Money Laundering Directive (AMLD6) and strict national regulator requirements. Banks minimize the risks of multi-million euro fines by shifting the burden of proving capital legality entirely onto the client.
The architecture of financial control in Spain is built around several key institutions and regulatory frameworks. The primary supervisory body is SEPBLAC (Servicio Ejecutivo de la Comisión de Prevención del Blanqueo de Capitales e Infracciones Monetarias). This executive service possesses extensive authority to monitor and investigate financial crimes. In 2026, SEPBLAC implemented updated protocols for the algorithmic analysis of transactions. All credit organizations operating in the country are legally obligated to utilize these protocols. These advanced systems are deeply integrated into internal AML (Anti-Money Laundering) frameworks. They provide automated, real-time scoring for every new client profile.
The country's central bank, Banco de España, regularly publishes circulars that severely tighten the liability of commercial banks for accepting "toxic" funds. Previously, fines for violating KYC (Know Your Customer) procedures were calculated in hundreds of thousands of euros. In 2026, these sanctions can reach up to 10% of a financial institution's annual global turnover. In extreme cases, the regulator can revoke the banking license entirely. Under such draconian conditions, compliance officers operate strictly on a principle of zero risk tolerance. Any minor doubt or inconsistency is automatically interpreted against the client.
The KYC procedure in 2026 has expanded far beyond simple identity verification. It now constitutes a deep, forensic audit of the applicant's entire economic life. The bank analyzes not only the current place of employment but also the retrospective accumulation of capital over the last five to ten years. The jurisdiction of tax residency is scrutinized meticulously. The presence of PEP (Politically Exposed Person) status triggers enhanced due diligence. Connections to high-risk countries and specific economic sectors are evaluated. Opening a bank account in Spain for non-residents 2026 is fundamentally impossible without passing this multi-factor audit. Banks utilize specialized global databases, such as World-Check and LexisNexis, to cross-reference all provided information.
Special attention is directed toward the specific profile of intended transactions. If the stated purpose of the account is transferring money to purchase an apartment, the bank will demand extensive proof. They require the preliminary reservation agreement (contrato de arras) and an independent valuation of the real estate object. Furthermore, they need confirmation that the transfer amount is strictly proportionate to the object's price and the client's declared historical income. Any discrepancy between these parameters acts as an immediate trigger to halt the onboarding process.
The architecture of financial control in Spain is built around several key institutions and regulatory frameworks. The primary supervisory body is SEPBLAC (Servicio Ejecutivo de la Comisión de Prevención del Blanqueo de Capitales e Infracciones Monetarias). This executive service possesses extensive authority to monitor and investigate financial crimes. In 2026, SEPBLAC implemented updated protocols for the algorithmic analysis of transactions. All credit organizations operating in the country are legally obligated to utilize these protocols. These advanced systems are deeply integrated into internal AML (Anti-Money Laundering) frameworks. They provide automated, real-time scoring for every new client profile.
The country's central bank, Banco de España, regularly publishes circulars that severely tighten the liability of commercial banks for accepting "toxic" funds. Previously, fines for violating KYC (Know Your Customer) procedures were calculated in hundreds of thousands of euros. In 2026, these sanctions can reach up to 10% of a financial institution's annual global turnover. In extreme cases, the regulator can revoke the banking license entirely. Under such draconian conditions, compliance officers operate strictly on a principle of zero risk tolerance. Any minor doubt or inconsistency is automatically interpreted against the client.
The KYC procedure in 2026 has expanded far beyond simple identity verification. It now constitutes a deep, forensic audit of the applicant's entire economic life. The bank analyzes not only the current place of employment but also the retrospective accumulation of capital over the last five to ten years. The jurisdiction of tax residency is scrutinized meticulously. The presence of PEP (Politically Exposed Person) status triggers enhanced due diligence. Connections to high-risk countries and specific economic sectors are evaluated. Opening a bank account in Spain for non-residents 2026 is fundamentally impossible without passing this multi-factor audit. Banks utilize specialized global databases, such as World-Check and LexisNexis, to cross-reference all provided information.
Special attention is directed toward the specific profile of intended transactions. If the stated purpose of the account is transferring money to purchase an apartment, the bank will demand extensive proof. They require the preliminary reservation agreement (contrato de arras) and an independent valuation of the real estate object. Furthermore, they need confirmation that the transfer amount is strictly proportionate to the object's price and the client's declared historical income. Any discrepancy between these parameters acts as an immediate trigger to halt the onboarding process.
Dossier preparation: Source of Funds document structure
The Source of Funds dossier structure requires providing apostilled documents translated by a sworn translator (traductor jurado), unequivocally confirming the economic nature of the capital's origin. The package is formed strictly individually depending on the tax residency jurisdiction and specific income type.
The concept of Source of Funds is the absolute cornerstone of modern banking compliance. It is crucial to distinguish between Source of Wealth (the origin of overall net worth) and Source of Funds (the origin of the specific money entering the account). The Spanish banking system requires confirmation of both categories. However, the primary focus always remains on the exact funds that will be physically transferred to Spain. The documentation must form an unbroken, logical chain. This chain must trace the money from the exact moment of income generation to the moment of its deposit into the sender's account in their home country.
The primary foundational document for any foreign national is the NIE (Número de Identidad de Extranjero). This is the official foreigner identification number. Without the original physical certificate of this number, initiating the banking procedure is impossible. Following this, the financial core of the dossier is systematically assembled. All documents issued outside of Spain must undergo a strict legalization procedure. For countries participating in the Hague Convention, this means obtaining an apostille. Subsequently, they must be translated by an official sworn translator registered with the Spanish Ministry of Foreign Affairs (MAEC). Standard notarized translations performed in the country of origin are categorically rejected by Spanish banks in 2026.
Below is a highly detailed matrix of document requirements based on the specific source of capital origin. This checklist (Document Pack) serves as the mandatory standard for passing compliance in leading institutions like Santander, BBVA, CaixaBank, and Sabadell.
The concept of Source of Funds is the absolute cornerstone of modern banking compliance. It is crucial to distinguish between Source of Wealth (the origin of overall net worth) and Source of Funds (the origin of the specific money entering the account). The Spanish banking system requires confirmation of both categories. However, the primary focus always remains on the exact funds that will be physically transferred to Spain. The documentation must form an unbroken, logical chain. This chain must trace the money from the exact moment of income generation to the moment of its deposit into the sender's account in their home country.
The primary foundational document for any foreign national is the NIE (Número de Identidad de Extranjero). This is the official foreigner identification number. Without the original physical certificate of this number, initiating the banking procedure is impossible. Following this, the financial core of the dossier is systematically assembled. All documents issued outside of Spain must undergo a strict legalization procedure. For countries participating in the Hague Convention, this means obtaining an apostille. Subsequently, they must be translated by an official sworn translator registered with the Spanish Ministry of Foreign Affairs (MAEC). Standard notarized translations performed in the country of origin are categorically rejected by Spanish banks in 2026.
Below is a highly detailed matrix of document requirements based on the specific source of capital origin. This checklist (Document Pack) serves as the mandatory standard for passing compliance in leading institutions like Santander, BBVA, CaixaBank, and Sabadell.
Confirming salary, dividends, and business sale
To confirm a salary, tax returns and 12-month bank statements demonstrating regular deposits are required. Dividends and business sales require providing audit reports, corporate resolutions, and share purchase agreements confirming real economic activity.
Analyzing income derived from standard employment is generally the least complex process. However, significant hidden obstacles exist even here. The compliance officer meticulously compares the declared corporate position with the stated income level. If a mid-level manager declares savings amounting to several million euros derived exclusively from a standard salary, this will trigger justified suspicion. In such specific cases, it is absolutely necessary to provide supplementary documents. These might include proof of corporate bonuses, Restricted Stock Units (RSU), or other forms of executive compensation. The bank statement must clearly reflect transactions from the employer with the appropriate payment purpose code.
The situation regarding corporate dividends is significantly more intricate. The bank does not merely record the fact of the payout. It deeply analyzes the specific company generating the profit. Opening a bank account in Spain for non-residents 2026 funded through dividends requires full disclosure of the corporate structure. If the company is registered in an offshore jurisdiction or features a complex multi-level ownership structure (holdings, trusts), the bank will demand extensive proof. They will request Certificates of Good Standing, Certificates of Incumbency, and financial statements prepared according to IFRS standards. The bank's ultimate goal is to verify that the company conducts real operational activity. It must have a physical office, actual employees, and verifiable counterparties, rather than being a shell company designed for fund transit.
Selling a business or a block of shares requires maximum analytical detail. The Share Purchase Agreement must contain clear transaction terms, a strict payment schedule, and verified details of all parties. The bank will mandatorily check the buyer of your business through open international registries. If the buyer is found on sanctions lists or is connected to high-risk jurisdictions, your funds will be immediately classified as "toxic." Consequently, the account opening application will be firmly denied.
Analyzing income derived from standard employment is generally the least complex process. However, significant hidden obstacles exist even here. The compliance officer meticulously compares the declared corporate position with the stated income level. If a mid-level manager declares savings amounting to several million euros derived exclusively from a standard salary, this will trigger justified suspicion. In such specific cases, it is absolutely necessary to provide supplementary documents. These might include proof of corporate bonuses, Restricted Stock Units (RSU), or other forms of executive compensation. The bank statement must clearly reflect transactions from the employer with the appropriate payment purpose code.
The situation regarding corporate dividends is significantly more intricate. The bank does not merely record the fact of the payout. It deeply analyzes the specific company generating the profit. Opening a bank account in Spain for non-residents 2026 funded through dividends requires full disclosure of the corporate structure. If the company is registered in an offshore jurisdiction or features a complex multi-level ownership structure (holdings, trusts), the bank will demand extensive proof. They will request Certificates of Good Standing, Certificates of Incumbency, and financial statements prepared according to IFRS standards. The bank's ultimate goal is to verify that the company conducts real operational activity. It must have a physical office, actual employees, and verifiable counterparties, rather than being a shell company designed for fund transit.
Selling a business or a block of shares requires maximum analytical detail. The Share Purchase Agreement must contain clear transaction terms, a strict payment schedule, and verified details of all parties. The bank will mandatorily check the buyer of your business through open international registries. If the buyer is found on sanctions lists or is connected to high-risk jurisdictions, your funds will be immediately classified as "toxic." Consequently, the account opening application will be firmly denied.
Based on the results of the first quarter of 2026, 73% of rejections when opening accounts for non-residents were directly linked to a break in the transaction chain. Clients provided flawless business sale contracts but could not document exactly how the money moved from the buyer to their personal account. This was especially true if escrow agents, cryptocurrency gateways, or transit accounts in third countries were utilized. Banco de España demands an unbroken documentary trail: from the initial contract to the final deposit into the account from which the transfer to Spain is planned. Any 'blind' transfer through unregulated platforms completely nullifies the legality of the entire capital in the eyes of Spanish AML control.
Cryptocurrencies and real estate: the regulator's position
In 2026, legalizing cryptocurrency income requires providing a full transaction audit through analytical platforms and confirming the payment of capital gains taxes. Income from real estate sales is confirmed by notarial deeds, registry extracts, and tax payment receipts.
With the full enforcement of the European MiCA (Markets in Crypto-Assets) regulation in 2026, the attitude of Spanish banks toward digital assets has become highly structured. However, it remains exceptionally strict. Cryptocurrency is no longer an absolute taboo. Yet, the process of passing the SEPBLAC bank compliance in Spain for crypto-derived income remains one of the most resource-intensive procedures. Banks demand absolute proof of the complete financial cycle: fiat-crypto-fiat.
The applicant is obligated to provide bank statements confirming the initial purchase of cryptocurrency using legal, verifiable funds (such as salary or documented savings). Next, a complete export of trading history from centralized exchanges (CEX) is required. These exchanges must hold valid licenses in highly reputable jurisdictions. If the funds were stored in cold wallets or participated in decentralized finance (DeFi) protocols, the bank will request a specialized report. This report must come from certified blockchain auditors, such as Chainalysis or Elliptic. It must unequivocally confirm the absence of any interaction with crypto mixers, darknet marketplaces, or sanctioned wallet addresses. The final, non-negotiable stage is the withdrawal of funds into fiat currency into an account at a regulated traditional bank. This must be followed by the payment of capital gains tax. Without a formal tax return reflecting the income from crypto assets, the Spanish bank will categorically refuse to accept the funds.
Income derived from the sale of real estate is a classic and generally understood source for banks. However, in 2026, the documentation requirements have tightened significantly. In addition to the standard purchase and sale agreement, the bank requires a historical financial certificate. You must prove how and with what specific funds the sold property was originally acquired many years ago. This is known as retrospective analysis. If the property was purchased fifteen years ago, you must provide at least indirect evidence of the legality of your income during that specific period. Furthermore, providing an official document confirming the payment of sales tax in the country where the property is located is mandatory. If there is no Common Reporting Standard (CRS) automatic tax information exchange agreement between the selling country and Spain, the bank will conduct its verification with double diligence. Opening a bank account in Spain for non-residents 2026 under such complex variables requires engaging specialized financial lawyers to draft comprehensive explanatory memorandums.
With the full enforcement of the European MiCA (Markets in Crypto-Assets) regulation in 2026, the attitude of Spanish banks toward digital assets has become highly structured. However, it remains exceptionally strict. Cryptocurrency is no longer an absolute taboo. Yet, the process of passing the SEPBLAC bank compliance in Spain for crypto-derived income remains one of the most resource-intensive procedures. Banks demand absolute proof of the complete financial cycle: fiat-crypto-fiat.
The applicant is obligated to provide bank statements confirming the initial purchase of cryptocurrency using legal, verifiable funds (such as salary or documented savings). Next, a complete export of trading history from centralized exchanges (CEX) is required. These exchanges must hold valid licenses in highly reputable jurisdictions. If the funds were stored in cold wallets or participated in decentralized finance (DeFi) protocols, the bank will request a specialized report. This report must come from certified blockchain auditors, such as Chainalysis or Elliptic. It must unequivocally confirm the absence of any interaction with crypto mixers, darknet marketplaces, or sanctioned wallet addresses. The final, non-negotiable stage is the withdrawal of funds into fiat currency into an account at a regulated traditional bank. This must be followed by the payment of capital gains tax. Without a formal tax return reflecting the income from crypto assets, the Spanish bank will categorically refuse to accept the funds.
Income derived from the sale of real estate is a classic and generally understood source for banks. However, in 2026, the documentation requirements have tightened significantly. In addition to the standard purchase and sale agreement, the bank requires a historical financial certificate. You must prove how and with what specific funds the sold property was originally acquired many years ago. This is known as retrospective analysis. If the property was purchased fifteen years ago, you must provide at least indirect evidence of the legality of your income during that specific period. Furthermore, providing an official document confirming the payment of sales tax in the country where the property is located is mandatory. If there is no Common Reporting Standard (CRS) automatic tax information exchange agreement between the selling country and Spain, the bank will conduct its verification with double diligence. Opening a bank account in Spain for non-residents 2026 under such complex variables requires engaging specialized financial lawyers to draft comprehensive explanatory memorandums.
How to avoid account blocking after transferring funds
Preventing a block requires pre-approving the incoming tranche with the bank's compliance department before the actual transfer of funds. The client must provide a draft real estate purchase agreement and an updated financial dossier to their personal manager.
Opening the account is merely the preliminary stage. The greatest number of critical problems arises at the exact moment of the actual money transfer for purchasing an apartment. The monitoring algorithms are calibrated so that any atypical deposit of a large sum into a non-resident's account automatically freezes the transaction pending investigation. Blocking a non-resident's account is the system's standard, automated defensive reaction.
To avoid the complete paralysis of your real estate deal, you must implement a strict pre-clearance protocol. Before pressing the "send" button in your home country's bank, the client or their authorized representative (such as an Angel Property broker) must send a formal notification to the Spanish bank regarding the planned incoming transfer. A complete package of updated documents must be attached to this notification. This includes the property reservation agreement (contrato de reserva) and the property registry extract (Nota Simple) for the acquired object. It also requires updated Source of Funds documents if more than three months have passed since the account was initially opened.
The compliance department thoroughly analyzes the provided data and issues a written or electronic confirmation of their readiness to accept the specific tranche. Only after receiving this explicit "green light" should you initiate the international transfer. It is critically important to ensure that the sender's banking details perfectly match the data of the Spanish account owner. Transfers from third parties (even close relatives) are strictly prohibited. Transfers from corporate accounts (if the Spanish account is opened for an individual) or through Electronic Money Institutions (EMI) without prior written approval will guarantee a problem. They will lead to the immediate return of funds to the sender and the unilateral closure of the Spanish account.
Furthermore, one must carefully consider transfer limits and banking tariffs. Some banks establish hidden commissions for crediting funds originating from outside the EEA. Proper payment routing and the correct selection of a correspondent bank allow you to avoid blocks. It also helps significantly save on transaction costs. Opening a bank account in Spain for non-residents 2026 implies building long-term, highly transparent relationships with the financial institution. In this dynamic, the bank acts not merely as a vault for funds, but as a fully-fledged, active partner in your real estate transaction.
Opening the account is merely the preliminary stage. The greatest number of critical problems arises at the exact moment of the actual money transfer for purchasing an apartment. The monitoring algorithms are calibrated so that any atypical deposit of a large sum into a non-resident's account automatically freezes the transaction pending investigation. Blocking a non-resident's account is the system's standard, automated defensive reaction.
To avoid the complete paralysis of your real estate deal, you must implement a strict pre-clearance protocol. Before pressing the "send" button in your home country's bank, the client or their authorized representative (such as an Angel Property broker) must send a formal notification to the Spanish bank regarding the planned incoming transfer. A complete package of updated documents must be attached to this notification. This includes the property reservation agreement (contrato de reserva) and the property registry extract (Nota Simple) for the acquired object. It also requires updated Source of Funds documents if more than three months have passed since the account was initially opened.
The compliance department thoroughly analyzes the provided data and issues a written or electronic confirmation of their readiness to accept the specific tranche. Only after receiving this explicit "green light" should you initiate the international transfer. It is critically important to ensure that the sender's banking details perfectly match the data of the Spanish account owner. Transfers from third parties (even close relatives) are strictly prohibited. Transfers from corporate accounts (if the Spanish account is opened for an individual) or through Electronic Money Institutions (EMI) without prior written approval will guarantee a problem. They will lead to the immediate return of funds to the sender and the unilateral closure of the Spanish account.
Furthermore, one must carefully consider transfer limits and banking tariffs. Some banks establish hidden commissions for crediting funds originating from outside the EEA. Proper payment routing and the correct selection of a correspondent bank allow you to avoid blocks. It also helps significantly save on transaction costs. Opening a bank account in Spain for non-residents 2026 implies building long-term, highly transparent relationships with the financial institution. In this dynamic, the bank acts not merely as a vault for funds, but as a fully-fledged, active partner in your real estate transaction.
Frequently Asked Questions
This section compiles direct, technically precise, and exhaustive answers to the most common questions non-residents have about interacting with the Spanish banking system in 2026.
Can I open an account remotely in 2026?
Yes, remote account opening is technically possible, but it is associated with severe restrictions. The procedure requires executing a notarized Power of Attorney (Poder Notarial) with an apostille in the name of a lawyer or agency representative in Spain. Additionally, the bank mandatorily conducts a real-time video identification procedure with the client to fulfill strict KYC requirements. However, it is crucial to note that remotely opened accounts frequently have strict limits on incoming transfers. These limits remain in place until the client's physical visit to the bank branch and the presentation of original physical documents.
Which banks accept documents in Russian/English?
No Spanish bank in 2026 accepts legal and financial documents in Russian. Absolutely all non-Spanish documents must be translated by an official sworn translator (traductor jurado) accredited in Spain. Documents in English may be accepted as a rare exception only in Private Banking divisions when managing capital exceeding one million euros. Standard retail branches (Retail Banking) strictly require the Spanish language for the entire Source of Funds package without exception.
How long does the compliance department review take?
The standard review period for a dossier by the compliance department ranges from 14 to 21 working days. This timeframe begins from the moment the complete and correctly translated document package is uploaded into the bank's internal system. In complex cases involving the analysis of multi-level corporate structures, trusts, cryptocurrency income, or funds from higher-risk jurisdictions, the review period is legally extended up to 45 working days. It is impossible to expedite this process, as SEPBLAC algorithms operate in a strict, unalterable queue.
Do I need an insurance policy to open an account?
From a strict legal perspective, imposing additional financial products when opening an account is unlawful. However, in practice, in 2026, retail banks in Spain utilize internal regulations stating that servicing non-resident accounts is unprofitable without cross-selling. Therefore, branch managers often set an unspoken condition. The account will be opened and approved much faster if the client purchases a health insurance policy (Seguro de Salud) or home insurance (Seguro de Hogar). Refusing to purchase insurance can lead to a formal denial of account opening under the pretext of "the client's profile not matching the bank's commercial policy."
What should I do if the bank requests additional information?
If the compliance officer requests additional documents (requerimiento de información), the client is obligated to provide them within a strictly established timeframe. This period usually ranges from 7 to 10 calendar days. Ignoring the request or providing incomplete information leads to the automatic suspension of the application review. In the case of an already active account, it leads to its immediate blocking. It is necessary to promptly contact your translator, prepare the required document, accompany it with a brief explanatory letter (in Spanish), and submit it to the manager.
How do I prove the origin of funds from selling stocks?
To confirm income from trading securities on the stock market, you must provide a comprehensive document package. First, brokerage statements covering the entire period of stock ownership are required. Second, a trade confirmation at the exact moment of selling the assets is necessary. Third, a bank statement confirming the withdrawal of funds from the brokerage account is mandatory. The most critical document is the tax return for the corresponding year. This return must officially record the capital gains income and confirm the fact of tax payment in the applicant's country of tax residency.
Opening a bank account in Spain for non-residents 2026 is not merely an administrative procedure. It is a comprehensive, forensic legal audit of your capital. Errors at this critical stage can jeopardize your entire real estate acquisition deal.
